Outlook · 2026-09-21
Vancouver FOB firms to eleven-hundred dollars while Shengyishe holds 7,669 yuan and AER July stock prints 11.11 Mt

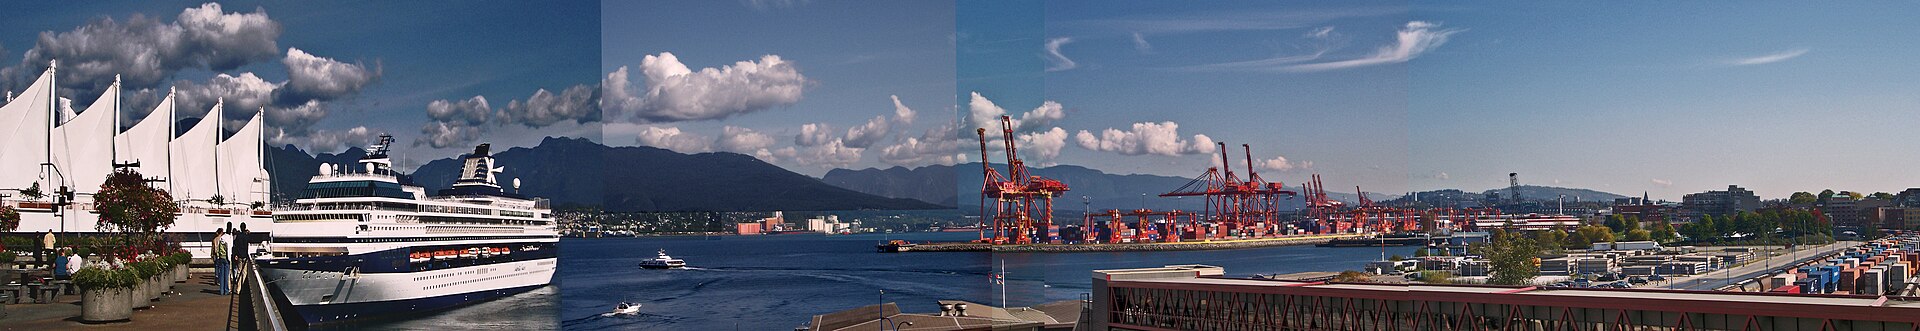
The North American sulfur desk entered the week of 21 September with the same February shock still governing seaborne balances, but with fresher open anchors on Pacific FOB, Chinese domestic correction, phosphate run cuts, and Alberta government inventory. BC Insight's 18 September price trends reported Vancouver FOB sulphur firmed fifty dollars per tonne at the upper end to a 1,100 to 1,200 dollars per tonne band on a confirmed Southern Africa sale, while Middle East spot was quoted at 865 to 900 dollars per tonne FOB and described as a three-month low. Hormuz congestion in the same note left roughly 400,000 tonnes of loaded backlog rising toward 600,000 tonnes on thirteen vessels waiting. BC Insight's 18 September market outlook, in the flat-to-soft camp Peter Harrison's CRU desk has used through late summer, said phosphate curtailments across Brazil, China, and Indonesian nickel demand were outweighing Hormuz delays in spot pricing because import buyers were hand-to-mouth or cutting runs. That split is the corridor read for Alberta: Pacific stems can hold eleven-hundred-dollar FOB ideas even when Chinese domestic benchmarks fall and Middle East contract postings ease on paper.
Chinese spot markets spent the third week of September correcting without clearing import parity. Shengyishe published its 21 September national sulfur benchmark at 7,669.00 yuan per metric tonne, unchanged on the day, with month-to-date loss at 8.14 percent versus the 1 September opening level of 8,349 yuan in the same open table. The flat print followed Longzhong's 20 September Zhenjiang granular quote near 7,200 yuan and keeps the domestic benchmark above that port reference while the move down from June highs near 9,875 yuan in BC Insight's weekly history continues. Shengyishe's 21 September trend note classified the market as a strong rebound in platform terminology even as direction stayed oscillation, with five-day spreads improving to negative 10.67 yuan from negative 17.67 yuan on 20 September while twenty-day spreads widened to negative 254.54 yuan. An evening spread update the same day put the ten-day minus twenty-day gap at negative 312.90 yuan, language the platform associates with accelerating downward momentum. For Vancouver netbacks the message is not collapse: it is buyers refusing to pay landed four-digit import math while port inventories and plant offers fall in yuan.
FDD-global's 20 September open commentary sharpened the phosphate side of that divergence. Major-port sulfur inventories were put at 926,800 tonnes as of 18 September, including 380,000 tonnes at Fangcheng, 200,000 at Zhanjiang, and 210,200 at Zhenjiang, down about 60 percent year on year but above the June-July trough near 750,000 tonnes. MAP capacity utilization was quoted near 47.91 percent and DAP near 43.95 percent with compound fertilizer near 34 percent, linking cuts to sulfur's share of production costs. Russia's sulfur export ban through December 2026 with only a 300,000-tonne low-grade quota under Resolution 1059 remained in force. On costs FDD contrasted QatarEnergy's September monthly sulfur at 880 dollars per tonne FOB with Kuwait August at 865 dollars FOB, estimated comprehensive CFR landed costs above 1,070 dollars per tonne at southern Chinese ports after freight and insurance, and said import trade was approaching break-even against Yangtze granular near 7,200 yuan. Longzhong's 20 September relay put Zhenjiang mainstream granular at 7,200 yuan, down 500 yuan week on week, with Shandong liquid sulfur at 7,600 to 7,625 yuan and Shandong Lihuayi cutting solid and liquid offers by 400 yuan to 7,600 yuan on 20 September to move inventory.
Atlantic phosphate economics remain the demand shock absorber that keeps Tampa contract language relevant even when Gulf spot softens on paper. Open reporting still puts third-quarter 2026 Tampa molten sulfur contracts at a record 705 dollars per long ton delivered, the last material open-news Tampa settlement cited by Argus on 13 July 2026. Fertilizer Daily via UkrAgroConsult on 18 September reported Tampa delivered sulfur above 1,100 dollars per tonne since May 2026 versus a prior-decade average near 172 dollars per long ton in the same chain, with Mosaic described running plants at roughly 50 percent rates in Florida and Louisiana. The Fertilizer Institute's August framing of Hormuz plus Russia as a dual-supplier failure and Mosaic's third-quarter molten settlement at 705 dollars per long ton remain the contract anchors on the US desk. Middle East monthly postings at 880 dollars per tonne FOB therefore still sit far below landed parity once Hormuz-route insurance surcharges that open reviews have cited near 200 dollars per tonne are included.
Canada's export lane stayed visible in August customs even as Chinese import totals cooled. Shanghai Metals Market published 20 September that China imported 272,323 metric tonnes of elemental sulfur in August, down 29.34 percent month on month and 65.03 percent year on year, with Canada listed among top origins alongside the UAE, South Korea, Japan, Kazakhstan, Vietnam, Singapore, and the Philippines. BC Insight's 18 September trends note had already put July Chinese imports at 385,403 tonnes, up 162 percent month on month but down 65 percent year on year, with January through July imports at 2.65 million tonnes, down 59 percent year on year. SMM's chain reviews continue to frame Canada as a swing supplier after Hormuz disruption, with 2025 exports at 4.25 million tonnes and early-2026 annualized values near 5.22 million tonnes in open accounts. The Vancouver Fraser Port Authority 2025 Statistics Overview, posted in March, still confirms sulphur through the port at 3,507,428 metric tonnes, up 5 percent year on year, with China at 1.30 million tonnes, Australia 597,000 tonnes, Indonesia 371,000 tonnes, and the United States 302,000 tonnes. Elemental sulfur under heading 2503 remained off Ottawa's September retaliation lists against US Section 338 duties, so Alberta forming plants still watch stem economics more than tariff headlines.
Alberta inventory finally has a verified_public government print on the desk. The Alberta Energy Regulator's current ST3 sulphur supply and disposition file, run date 27 August 2026, puts province-wide closing inventory at 11,109,610.9 tonnes for July 2026, about 11.11 million tonnes in desk rounding. Year-to-date production through July was 2,430,276.0 tonnes with July production at 378,614.8 tonnes; year-to-date removals were 1,127,009.9 tonnes with July removals at 183,631.4 tonnes. That July 2026 close replaces the July 2025 trade-press anchor of 11.66 million tonnes that had been the last widely cited draw story tied to lowest stocks since May 2019. The new print confirms stocks remain elevated in absolute terms even as exports and removals run under 2025's remelt-and-stem economics. Recovery still tracks bitumen throughput, not the sulfur bid, and BC Insight's oil-sands contribution estimates near 3.0 million tonnes annually still frame oil sands as the majority of national elemental output.
Freight netbacks keep Pacific stems bid on delivered math, not Gulf postings alone. Public reference hubs on the desk, open-news and industry_estimate anchors only, show FOB Vancouver granular in a 1,100 to 1,200 dollars per tonne band as of 18 September 2026 per BC Insight's confirmed Southern Africa sale narrative, while FOB US Gulf granular mid about 1,125 dollars per tonne as of 1 July 2026 remains the last structured Gulf anchor in the platform series. SunSirs' mid-September import reviews still put China granular CFR at 1,000 to 1,050 dollars per tonne at the top of a wide 525 to 1,050 dollars per tonne import window. SMM's 18 September sulphuric acid weekly review put CFR India near 1,050 dollars per tonne after a twenty-five dollar cut from 1,075 dollars and CIF Indonesia near 1,005 dollars per tonne, down twenty dollars week on week. SMM announced a new CFR China sulfur assessment from 25 September on 8,000 metric tonne minimum lots, which will add a second open China import marker without replacing licensed PRA weekly grids. USGS Mineral Industry Surveys remain paused during the ScienceBase migration, so monthly US production prints are still December 2025 at latest posted.
BC Insight's 18 September acid trade insight said China's unofficial sulphuric acid export halt from May through year-end 2026 removes an estimated 2.8 million metric tonnes from the traded acid pool in 2026, with Indonesian nickel buyers active in spot acid as smelter supply lagged. That acid tightness feeds back to elemental sulphur scarcity in HPAL and phosphate chains even as Chinese elemental benchmarks fall. Hormuz commodity transits in single digits through mid-September and backlog estimates between 400,000 and 450,000 tonnes confirm Middle East seaborne recovery is still a freight and insurance problem, not a solved diplomatic problem, consistent with Reuters counts of four commodity vessel crossings on 15 and 16 September against a ten-day average near eighteen.
The corridor read into 21 September is therefore split rather than resolved. Alberta recovered sulfur still leaves mainly through the Vancouver stem at FOB ideas that BC Insight now places at 1,100 to 1,200 dollars per tonne. World supply shocks show up there as stem tightness, remelt draws, and Gulf-versus-Pacific basis even as Chinese domestic benchmarks hold near 7,669 yuan and port granular quotes near 7,200 yuan. AER July 2026 closing stock at 11.11 million tonnes is the verified inventory anchor. Tampa at 705 dollars per long ton and phosphate idling above 1,000 dollar sulfur costs are the Atlantic prints. Canada on a multi-year export upswing with August customs still listing Canadian origins in China's shrinking import book is the Pacific print.
Key points
- BC Insight 18 Sep: Vancouver FOB $1,100–1,200/t on Southern Africa sale; ME spot $865–900/t FOB (3-month low); Hormuz backlog ~400 kt rising toward ~600 kt on 13 waiting vessels.
- BC Insight 18 Sep outlook: global sulphur flat to soft; phosphate curtailments outweigh Hormuz delays in spot pricing; China/Med softer on thin liquidity.
- Shengyishe 21 Sep: benchmark 7,669 yuan/t flat; MTD −8.14% vs 1 Sep open 8,349 yuan/t; conflicting intraday trend vs evening spread widening signals.
- FDD 20 Sep: major-port stocks 926,800 t (18 Sep); MAP ~47.9% utilisation, DAP ~44.0%; import CFR landed >~$1,070/t vs Zhenjiang granular ~7,200 yuan/t near break-even.
- Longzhong 20 Sep: Zhenjiang granular 7,200 yuan/t (−500 yuan w/w); Lihuayi cut offers to 7,600 yuan/t on 20 Sep.
- SMM 20 Sep: China Aug sulfur imports 272,323 t (−65% y/y); Canada among listed origins.
- AER ST3 Jul 2026: Alberta closing inventory 11,109,610.9 t (~11.11 Mt); Jul production 378,614.8 t; Jul removals 183,631.4 t (verified_public, run date 27 Aug 2026).
- Last open-news Tampa Q3 molten print: $705/lt delivered (Argus, 13 Jul 2026). ME Sep contract reference 880/t FOB (SunSirs/FDD).
- UNCERTAIN: whether SMM's new CFR China marker from 25 Sep shifts Pacific netback quoting; whether insured bulk sulfur transits accelerate before year-end; whether Chinese autumn phosphate buying reverses domestic correction.
30-day watchlist
- Shengyishe benchmark and spread prints versus Longzhong Zhenjiang granular and FDD port-inventory updates.
- BC Insight Vancouver FOB band and Hormuz backlog revisions versus India CFR near $1,050/t in SMM weekly reviews.
- AER ST3 August closing inventory when the current PDF updates beyond July 2026.
- SMM CFR China sulfur launch from 25 September and first Friday publication at noon Beijing time.
- VFPA monthly updates and StatCan HS 2503 tables that change 2026 export pace versus 2025.
- Public confirmation of Gulf sulfur loadings returning above 1 Mt/month or further Mosaic/phosphate run cuts.
- Covered-list and retaliation calendar text for any HS 2503 listing.
Sources
- Price trends 80 (BC Insight, 18 Sep 2026)
- Market outlook 82 (BC Insight, 18 Sep 2026)
- China export halt reshapes acid trade in 2026 (BC Insight, 18 Sep 2026)
- Shengyishe sulfur benchmark 21 Sep
- Shengyishe trend 21 Sep
- Shengyishe spread 21 Sep evening
- FDD sulfur reassessing short-term correction (20 Sep 2026)
- SMM China sulfur and sulphuric acid trade August 2026
- Longzhong/Zhenjiang granular weakness (Gate.com relay, 20 Sep 2026)
- SMM sulphuric acid weekly review (18 Sep 2026)
- Sulfur shortage threatens US phosphate prices (UkrAgroConsult / Fertilizer Daily, 18 Sep 2026)
- Tampa 3Q liquid sulphur price hits record $705/lt (Argus open news)
- AER ST3 Sulphur current PDF
- Sulfur Wire desk intel 2026-09-18 through 2026-09-21
Public reference summary. Weekly PRA assessments require a commercial license. Not investment advice.
Public-source summary. Not investment advice. Unsubscribe from the email edition: reply UNSUBSCRIBE or email [email protected].